
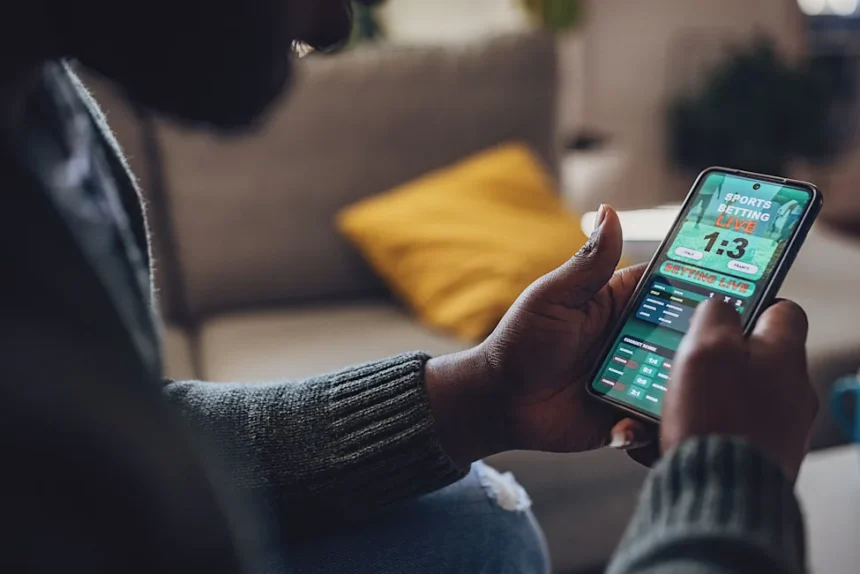
Imagine you are sitting in a coffee shop, scrolling through your phone while waiting for your latte. You open your investment app, and instead of seeing a boring line graph slowly climbing over decades, you see a notification that your portfolio jumped 15% overnight because of a meme stock surge. It feels like winning the lottery, doesn’t it? That rush of dopamine is real, and for many young people, it has become addictive. But here is the hard truth: Gen Z investors are gambling with their financial futures, often mistaking high-risk speculation for smart investing.
- The Blur Between Investing and Speculation
- Why the Urge to Take Massive Risks Is So Strong
- The Hidden Costs of High-Risk Trading
- How to Shift From Gambler to Investor
- Define Your “Play Money” Bucket
- Educate Yourself on Fundamentals
- Automate the Boring Stuff
- Re-evaluate Your Goals
- Building a Future You Can Count On
It is easy to see why this is happening. You grew up watching traditional paths to wealth like buying a house or sticking to a 40-year career at one company crumble under the weight of inflation and soaring living costs. When the “safe” route feels impossible, the risky route starts to look like the only option. Social media feeds are filled with stories of teenagers turning a few hundred dollars into millions overnight, making steady, long-term growth look boring and ineffective.
In this article, we are going to have an honest conversation about what is really happening with your investment money. We will explore the thin line between investing and gambling, why the current market environment encourages risky behavior, and how you can shift your mindset to build actual, lasting wealth. You do not need to quit the market or stop taking risks entirely, but you do need to understand the game you are playing so you do not lose your shirt before you even get started.
The Blur Between Investing and Speculation
Let’s be clear about the difference between these two concepts, because the line has become incredibly blurry on your smartphone screen. Traditional investing is like planting an oak tree. You put a seed (your money) in the ground, you water it (add more funds), and you wait years for it to grow strong and provide shade (passive income). It is slow, sometimes boring, but generally reliable.
Speculation, on the other hand, is like betting on a horse race. You are not concerned with the long-term health of the horse; you just want to pick the winner before the race ends so you can cash out immediately. When Gen Z investors are gambling, they are often treating the stock market like a casino floor. They buy assets not because the underlying company is healthy or profitable, but because the price is moving fast and everyone on Twitter is talking about it.
The Gamification of Finance
Part of the problem lies in the tools you use. Modern trading apps are designed to feel like video games. They use bright colors, confetti animations when you make a trade, and push notifications that create a sense of urgency. These features trigger the same psychological responses as slot machines. When you see a green arrow pointing up, your brain releases dopamine, encouraging you to make another trade. This design makes it incredibly easy to treat your investment money as chips at a poker table rather than resources for your future.
Furthermore, the barrier to entry has vanished. You can start trading with five dollars and execute trades in seconds from your bed. While this accessibility is great for democracy, it also removes the friction that used to force people to think twice before making a risky move. When trading is this easy, it becomes impulsive.
Why the Urge to Take Massive Risks Is So Strong
It is unfair to simply blame young people for being reckless. The economic reality you face is drastically different from what your parents or grandparents experienced. When traditional avenues for building wealth seem blocked, extreme risk-taking feels like a rational response.
The Housing Market Lockout
For previous generations, buying a home was the primary way to build net worth. It was a forced savings account that usually appreciated over time. Today, with housing prices skyrocketing and wages struggling to keep up, that ladder has been pulled up. If saving 20% for a down payment feels mathematically impossible, why bother saving slowly at all? Many young investors feel that the only way to catch up is to hit a “home run” in the stock market. They believe they need to double or triple their money quickly just to afford a basic life.
The Fear of Missing Out (FOMO)
Social media amplifies this pressure. Algorithms are designed to show you the most sensational content. You rarely see posts from people who made a steady 7% return this year; those stories are boring. Instead, your feed is flooded with screenshots of 500% gains on crypto coins or obscure tech stocks. This creates a distorted view of reality where everyone seems to be getting rich except you. This fear of missing out drives you to chase trends, often buying in right before the bubble bursts.
The All-or-Nothing Mentality
When the gap between where you are and where you want to be feels insurmountable, an “all-or-nothing” mentality takes over. If playing it safe means you will never afford a home or retire comfortably, then playing it safe feels like losing by default. This mindset pushes Gen Z investors are gambling behaviors into the mainstream. It is not just about greed; it is often about desperation and a desire to regain control over a financial future that feels uncertain.
The Hidden Costs of High-Risk Trading
While the potential for quick gains is exciting, the downsides are severe and often underestimated. Gambling with your investment money carries costs that go far beyond just losing a few dollars on a bad trade.
Erosion of Principal
The most obvious risk is losing your capital. In a casino, the odds are mathematically stacked against you. In the stock market, when you are trading based on hype rather than fundamentals, the odds are similarly poor. Day trading and speculative betting have a high failure rate. If you lose a significant chunk of your savings early on, it can take years to recover, setting you back precisely when you should be compounding your growth.
Emotional Burnout
Constantly monitoring volatile assets is exhausting. When your financial security is tied to the minute-by-minute fluctuations of a meme coin, your stress levels skyrocket. This emotional rollercoaster can lead to poor decision-making, such as panic selling at the bottom or doubling down on a losing bet out of stubbornness. Over time, this stress can damage your relationship with money entirely, making you afraid to invest even in safe, sensible options later.
Opportunity Cost
Every dollar you sink into a high-risk gamble is a dollar that isn’t working for you in a diversified, long-term portfolio. While you are chasing the next big thing, you might be missing out on the steady, reliable growth of the broader market. History shows that time in the market beats timing the market almost every time. By focusing on short-term wins, you sacrifice the power of compound interest, which is the true engine of wealth creation.
How to Shift From Gambler to Investor
The goal here is not to shame you for wanting to grow your wealth. Taking risks is a necessary part of investing. The key is to make those risks calculated and intentional rather than impulsive and emotional. You can still participate in exciting markets without betting your entire future on them.
Define Your “Play Money” Bucket
One effective strategy is to separate your finances into two distinct buckets. The first bucket is your serious investment money. This goes into diversified index funds, retirement accounts, and stable assets intended for long-term goals like retirement or a home. This money is off-limits for day trading. The second bucket is your “play money.” This is a small percentage of your income say, 5% to 10% that you are fully prepared to lose. You can use this to trade crypto, individual stocks, or other speculative assets. This allows you to scratch the itch for excitement without jeopardizing your financial security.
Educate Yourself on Fundamentals
Before you put a single dollar into an asset, do your homework. What does the company actually do? Do they make a profit? What is the total supply of that cryptocurrency? Understanding the fundamentals helps you distinguish between a genuine opportunity and a pump-and-dump scheme. Knowledge is your best defense against manipulation. If you cannot explain why an asset should be worth more in five years, you are probably gambling, not investing.
Automate the Boring Stuff
Remove the emotion from your long-term investing by automating it. Set up automatic transfers from your checking account to your investment accounts every month. This strategy, known as dollar-cost averaging, ensures you are consistently buying regardless of market conditions. It takes the decision-making out of your hands and prevents you from trying to time the market. When the boring stuff is handled automatically, you can focus your energy on learning and growing your career, which is often the best investment you can make.
Re-evaluate Your Goals
Take a moment to reflect on what you actually want. Is your goal to get rich next Tuesday, or to build a life of freedom and stability over the next decade? Quick riches are rare and fleeting; sustainable wealth is built brick by brick. Remind yourself that slow and steady wins the race. There is no shame in average returns if they lead to a secure future.
Building a Future You Can Count On
It is understandable why the allure of quick wealth is so strong when the traditional path feels broken. But remember, the stories you see online are the exceptions, not the rule. For every person who struck gold on a meme stock, thousands lost their savings trying to do the same. You do not have to choose between being bored and being broke. There is a middle path that offers both excitement and security.
By recognizing that Gen Z investors are gambling too often with money they cannot afford to lose, you can take a step back and reassess your strategy. Protect your core investment money with disciplined, long-term habits, and satisfy your urge for risk with a small, controlled portion of your portfolio. Wealth building is a marathon, not a sprint. Be kind to your future self by making choices today that will allow you to sleep soundly tonight and thrive tomorrow. You have the power to write your own financial story, so make sure it is one you will be proud to read in twenty years.